The Bond Market Doesn't Give a Fuck About Your Vision
The stock market loves a good story. The bond market wants to know when it's getting its money back.
I was listening to Ed Zitron on a podcast recently, talking about the seemingly endless amounts of money being poured into the AI industry, when he dropped an observation that struck me as both funny and remarkably insightful.
He said, roughly, that the stock market measures how excited you should be, while the bond market measures how scared you should be.
I laughed, but then I thought about it some more.
That's a pretty damn good way to explain the difference between two financial markets that are frequently lumped together as simply "Wall Street."
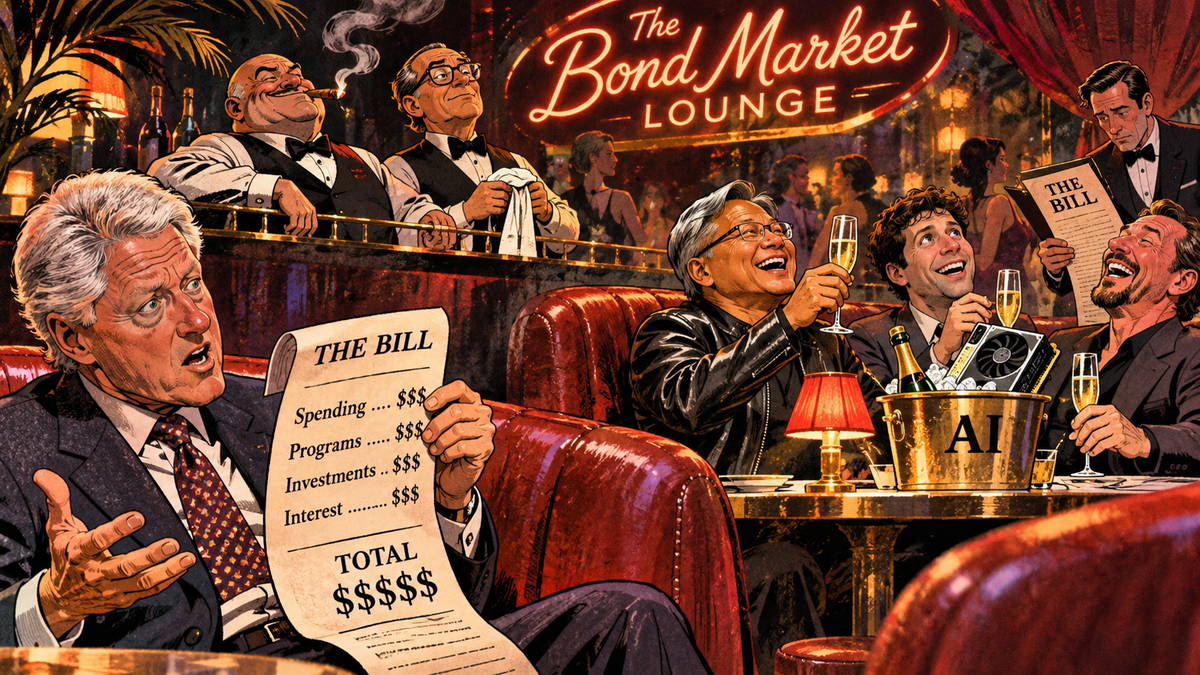
And it reminded me of a story from the early days of Bill Clinton's presidency, when a newly elected president discovered that winning an election didn't necessarily mean he got to do what he wanted.
Not when the bond traders had something to say about it.
Bill Clinton meets the real boss
In January 1993, Bill Clinton was preparing to take office. He'd campaigned on rebuilding the economy, investing in infrastructure, improving education, and generally reversing what he saw as the economic mistakes of the Reagan and Bush years.
He had an agenda, and he'd just won the presidency. Time to get to work, right?
Well, not so fast.
His economic advisers explained that the federal deficit was a serious problem and that implementing his ambitious spending plans without a credible deficit-reduction strategy could cause the bond market to revolt.
Investors might demand higher yields to hold Treasury bonds, pushing up borrowing costs throughout the economy. That could undermine the very growth Clinton needed to make his program successful.
According to Bob Woodward's book The Agenda, Clinton was furious. He demanded to know whether his economic program and reelection really depended on the Federal Reserve and a bunch of fucking bond traders.
Apparently, the answer was yes.
Now, this wasn't quite as simple as Wall Street dictating policy to an innocent president. Clinton knew about deficits, and his own advisers were making an economic argument about interest rates and growth. The precise effects of deficit reduction were uncertain, too.
But the larger point was unmistakable. A newly elected president, with all the power and prestige of that office, was being told that a collection of investors could make his life miserable if they didn't like his fiscal policies.
There's a lesson here for today's more exuberant Democrats and progressives, particularly those anticipating new governing majorities and dreaming of a wholesale renovation of the American social contract.
Winning an election is one thing. Financing your ambitions is another.
You can campaign on universal healthcare, expansive social programs, massive public investment, and a fundamental redistribution of economic opportunity. You might even win a genuine mandate to pursue those things.
But that doesn't make the financial constraints disappear.
We've developed a peculiar relationship with government revenue in this country. One side of our politics treats raising taxes as a mortal sin. The other can sometimes sound like the person insisting they couldn't possibly be overdrawn because they still have checks left.
And yes, taxing the wealthy is a perfectly legitimate part of the conversation. But an expansive, durable social contract requires an expansive, durable revenue base. That's rather more politically difficult than promising to make billionaires pick up the entire tab.
To be clear, the federal government isn't a household balancing a checkbook. It can borrow, and deficits can be perfectly appropriate, particularly during recessions or when financing investments that will improve future economic capacity.
But borrowing isn't a substitute for having an actual plan to finance the commitments you're making.
The bond market doesn't get to decide what kind of society Americans should build. But neither does winning an election make the financial constraints disappear.
Clinton learned that lesson before he even took office. It's worth remembering for anyone preparing to celebrate a future electoral victory as though the hard part were over.
James Carville, Clinton's political strategist, famously joked that if reincarnation were possible, he'd like to come back as the bond market.
Why?
Because the bond market could intimidate everybody.
Think about that for a moment.
The president commands the military, signs legislation, appoints judges, and has the most powerful political megaphone on the planet.
But a bunch of people buying and selling government debt can make him rethink his agenda.
That's a hell of a thing.
Sweaty's Corner doesn't have a marketing budget or an algorithm pushing it into anyone's feed. It has readers who share it. If this one landed, sending it to someone who'd get something out of it — or subscribing so the next one finds you directly — genuinely moves the needle.
The difference between dreams and obligations
Back to Zitron.
The stock market and the bond market are looking at the same companies, but they're asking fundamentally different questions.
When you buy stock in a company, you're buying a piece of its future. If the company grows dramatically, your investment can grow along with it.
The theoretical upside is unlimited.
This makes equities particularly susceptible to compelling stories about the future.
A company might revolutionize transportation. Or cure cancer. Or completely transform how human beings work, communicate, and create.
And if you believe that story, you can justify paying an extraordinary amount of money today for profits that might arrive years down the road.
Hell, those profits might never arrive.
But if enough people believe the story, the stock can rise anyway. For quite a while.
The bond market is different.
When you buy a bond, you're generally lending money in exchange for a defined stream of interest payments and the eventual return of your principal.
Your upside is limited. If the company becomes the most successful enterprise in human history, congratulations. You still get your contracted payments.
But if the company falls apart, you could lose a substantial portion of your investment.
That's an entirely different incentive structure.
The equity investor wants to know how magnificent the future could be.
The bond investor wants to know whether the borrower can survive if that future turns out to be considerably less magnificent.
And that distinction matters enormously.
Of course, bond investors aren't some uniquely brilliant class of financial savants. They've financed their share of spectacular disasters, from junk-bond excesses to the mortgage securities that helped blow up the global financial system in 2008.
Sometimes the bond market is just as gullible as the stock market.
The difference is that debt eventually demands cash.
You can't pay the interest on a bond with a PowerPoint presentation about your total addressable market.
Enter the AI revolution
Which brings us to the current AI investment frenzy.
I've written a fair amount about the extraordinary sums being committed to AI infrastructure, and I remain deeply skeptical that the economics will ultimately justify the scale and pace of the investment.
Not because AI is useless. Far from it.
I use these tools, find them genuinely valuable, and believe they'll become an important part of how we work.
But there's a rather large difference between believing a technology will be important and believing that every company investing hundreds of billions of dollars in it will earn an attractive return.
And this is where the equity and bond market distinction becomes particularly interesting.
For much of the AI boom, the story has been dominated by equity valuations.
NVIDIA is selling the picks and shovels. Microsoft, Google, Amazon, Meta, and Oracle are building the infrastructure. OpenAI, Anthropic, and a growing collection of other companies are developing and selling the models.
The spending is extraordinary, and the promises are even bigger.
We are told AI will transform virtually every industry, create enormous new markets, and usher in a period of productivity growth unlike anything we've previously experienced.
Maybe it will.
But that doesn't answer the financial questions:
- How much will customers actually pay for these services?
- How much will it cost to deliver them?
- How quickly will the hardware become obsolete?
- What happens when competing models become sufficiently good that customers stop paying premium prices for frontier capabilities?
- And what happens if the infrastructure is built faster than demand materializes?
These aren't arguments that AI will fail. They're questions about whether the people paying for its development will ever make money.
Those are not the same thing.
The bond market begins asking uncomfortable questions
Here's where the story gets particularly timely.
As the AI buildout has accelerated, companies have increasingly turned to debt financing to help fund the enormous infrastructure commitments.
According to a November 10, 2026 analysis from Bessemer Trust, six major hyperscalers issued more than $250 billion in investment-grade bonds during 2026 through the period covered by its analysis.
That's compared with $93 billion in 2025 and just $19 billion in 2024.
A remarkable increase.
And investors are beginning to distinguish between borrowers with enormous existing cash flows and those whose ability to repay depends much more heavily on future AI demand.
On November 9, Reuters reported that banks and credit investors were becoming more reluctant to take on additional AI-related debt exposure.
The questions have become more pointed. Lenders are examining projected cash flows, construction schedules, guarantees, and the circumstances under which customers might cancel or reduce their commitments.
Imagine that.
Someone wants to know whether the business can actually pay its bills.
There's a particular problem with financing AI infrastructure that I think deserves more attention: the mismatch between the useful economic life of the hardware and the duration of the financial commitments.
A data center is a long-lived asset. The building, electrical infrastructure, cooling systems, and land can remain productive for decades.
But the GPUs inside that building are another matter.
We're in an industry where new generations of accelerators can deliver enormous improvements in performance and efficiency. And the price of delivering AI inference continues to face significant downward pressure.
So what happens if you've financed a massive installation of today's technology over several years, only to find that tomorrow's hardware makes the economics considerably less attractive?
You still owe the money.
The debt doesn't become cheaper because NVIDIA released a newer GPU.
Nor does it disappear because an open-weight model can deliver a perfectly acceptable result at a fraction of the cost of your expensive frontier system.
This isn't an insurmountable problem. Older hardware can remain productive, particularly for less demanding workloads. And the biggest technology companies have substantial existing businesses that can support their investments even if AI returns disappoint.
But for the more highly leveraged companies whose entire business depends on renting AI computing capacity, the risk is considerably more acute.
It's one thing to promise extraordinary growth.
It's another to borrow billions against the assumption that the growth will arrive on schedule.
Markets aren't referees
Now, I don't want to turn this into some romantic celebration of the bond market as the last bastion of financial sanity.
It isn't.
Bond investors can be spectacularly wrong, and rising yields don't automatically mean the people selling bonds have made bad decisions.
Sometimes markets panic. Sometimes they overreact. Sometimes they punish perfectly reasonable investments because investors are frightened, overexposed, or simply need to raise cash.
And sometimes the bond market's demands can impose real costs on society.
Clinton's experience illustrates that last point rather well. The desire to satisfy bond investors helped steer his administration toward deficit reduction and away from some of the public investment ambitions he'd brought into office.
Whether that was the right economic choice remains a legitimate subject of debate.
The bond market isn't a democratic institution. It doesn't vote on whether a public investment would improve people's lives.
It prices financial risk.
Those two things are not necessarily aligned.
But that is also why its influence is so significant.
A government, corporation, or entrepreneur can make an extraordinarily persuasive argument about the future. They can convince voters, shareholders, employees, customers, and perhaps even themselves.
Eventually, though, if they depend on borrowed money, somebody has to agree to lend it.
And those lenders are entitled to ask some deeply inconvenient questions.
Reality eventually sends an invoice
I keep coming back to the distinction between a technology succeeding and the companies funding it succeeding.
The internet was genuinely revolutionary. It transformed communications, commerce, entertainment, and virtually every other part of modern life.
That didn't make buying shares in every internet company in 1999 a good investment.
Nor did it prevent enormous amounts of money from being wasted on businesses and infrastructure that were built on wildly optimistic assumptions about adoption and revenue.
I suspect AI will follow a similarly uneven path.
There will be enormous winners. There will be companies that spend fortunes and have surprisingly little to show for it. And there will be plenty of useful technology that becomes so inexpensive and commonplace that the original investors struggle to capture the value they helped create.
The benefits to society and the returns to investors are two different ledgers.
For now, the equity market continues to entertain the possibility of an extraordinarily profitable AI future, while the credit markets are becoming more discriminating about who gets to borrow, how much, and on what terms.
That doesn't mean the AI boom is about to collapse.
It means that the financing is beginning to face a different kind of scrutiny.
And when I think about Bill Clinton discovering the power of bond traders more than thirty years ago, I can't help but see the parallels.
It doesn't matter whether you're a newly elected president promising to rebuild America or a technology executive promising to reinvent civilization.
You can have the most compelling vision in the world.
You can have enthusiastic supporters, breathless press coverage, and a stock price that seems to defy gravity.
But eventually somebody is going to ask how you intend to pay for it.
And the interest payment is still due Thursday.